Most standard home policies cover sudden and accidental water damage — a burst pipe, a storm event, an appliance failure. What’s usually excluded is gradual damage from a leak you knew about or should have known about. The difference between a paid and a disputed claim is often the evidence.
Document before anything moves
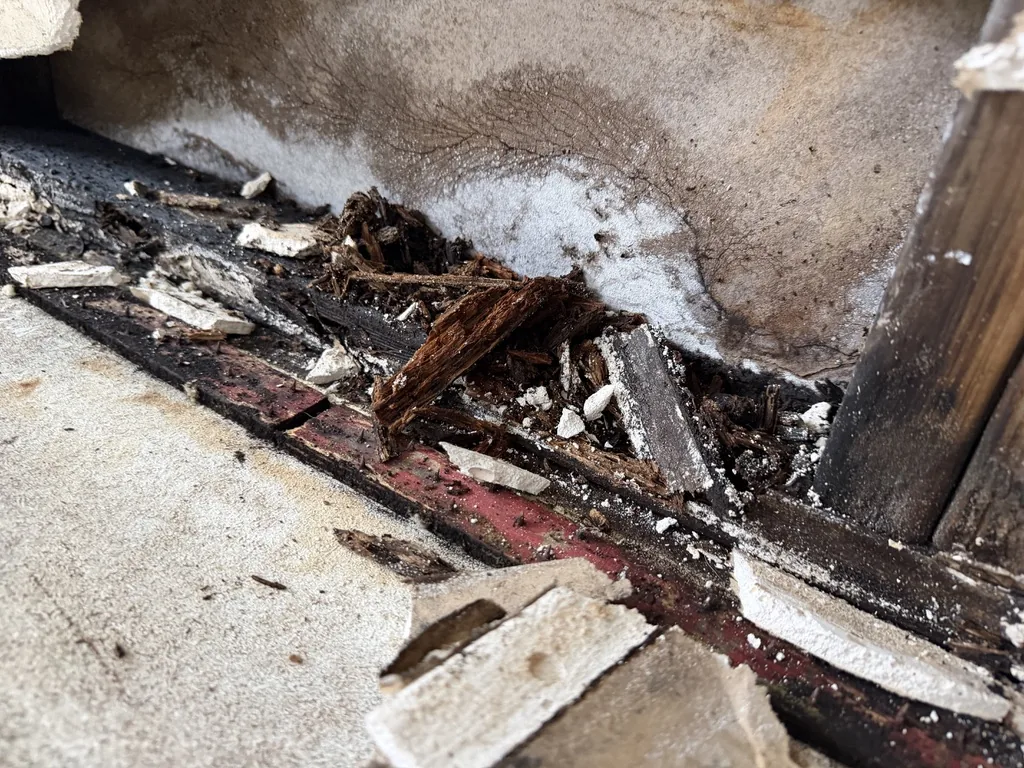
Photograph the damage before it’s cleaned or dried, and note the cause and the date it happened. Once a room is dried out, it’s much harder to show an insurer what it looked like.
The professional documentation that carries weight
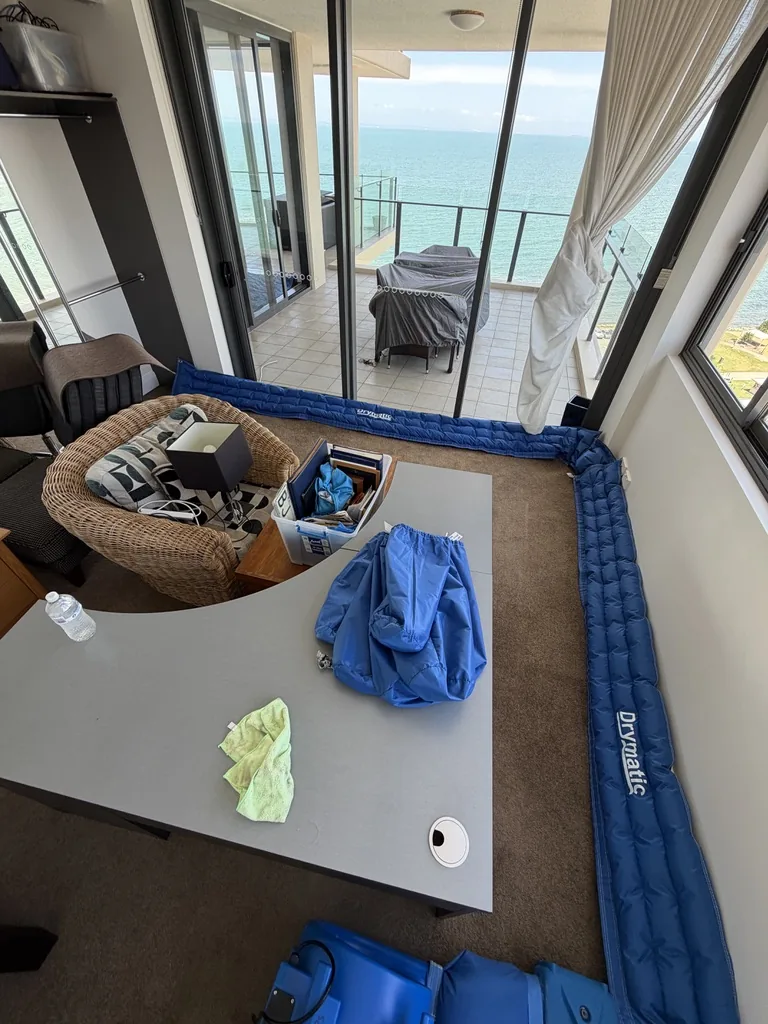
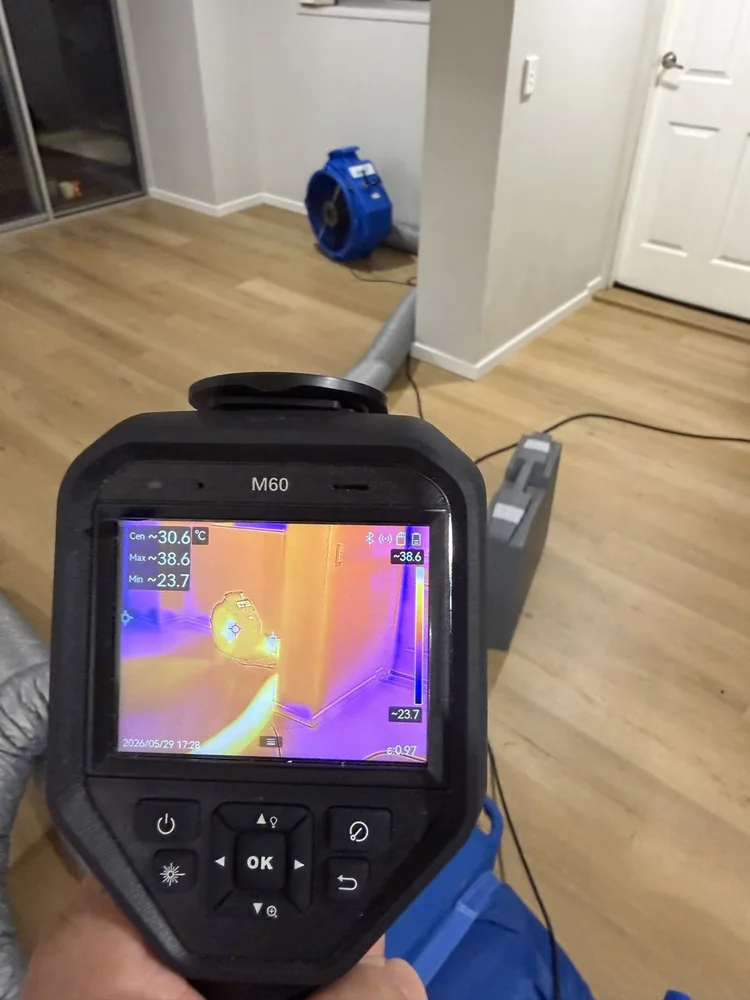
Moisture mapping reports, thermal images, daily drying logs and a final drying certificate are the records a major Australian insurer recognises. Work carried out and documented to industry standard is far harder to dispute than a clean-up with a few phone photos.
We’re not your insurer
To be clear: we provide the works and the documentation to support your claim — we don’t decide it. Acceptance, coverage and payment are between you and your insurer under your policy. But solid documentation gives your claim its best chance.
Related infographicThe insurance documentation checklistGeneral information only — every property is different, and nothing here replaces a professional, on-site assessment.